The next new position in our Paid-to-Play portfolio is:
For access to JC and Sean’s P2P options strategies, you must be a premium member of All Star Options P2P. Please login below.
Expert technical analysis of financial markets by JC Parets
The next new position in our Paid-to-Play portfolio is:
For access to JC and Sean’s P2P options strategies, you must be a premium member of All Star Options P2P. Please login below.
The next new position in our Paid-to-Play portfolio is: [Read more…]
There are pros and cons to both Naked Short Strangles and Iron Condors.
Both are typically done as credit spreads when we hope to collect some delta-neutral premium on a bet that implied volatility will decline and/or the underlying will trade in a range for a little while.
Where they differ significantly is in the risks involved in holding each type of trade.
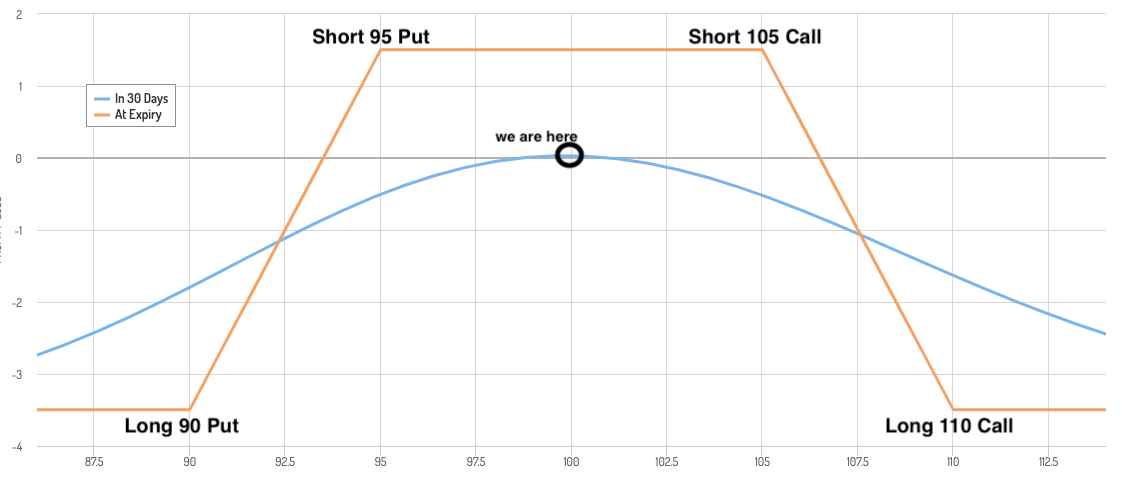
In an Iron Condor, we have defined risk because we are holding long out-of-the-money calls and puts. We know the absolute most we can lose. But those long calls and puts cost money and change the math, decreasing our win rate and often our total profits. There is a price to be paid for safety. And I’m not saying this price isn’t worth it. But it’s important to know it exists.
An example of a PnL curve in an Iron Condor position.
In a Naked Short Strangle, we do not have a defined risk. We are holding naked short puts and naked short calls in which we could potentially suffer an unlimited loss in an extreme market move (or an extreme bout of stubbornly NOT executing our stop-loss plan!).
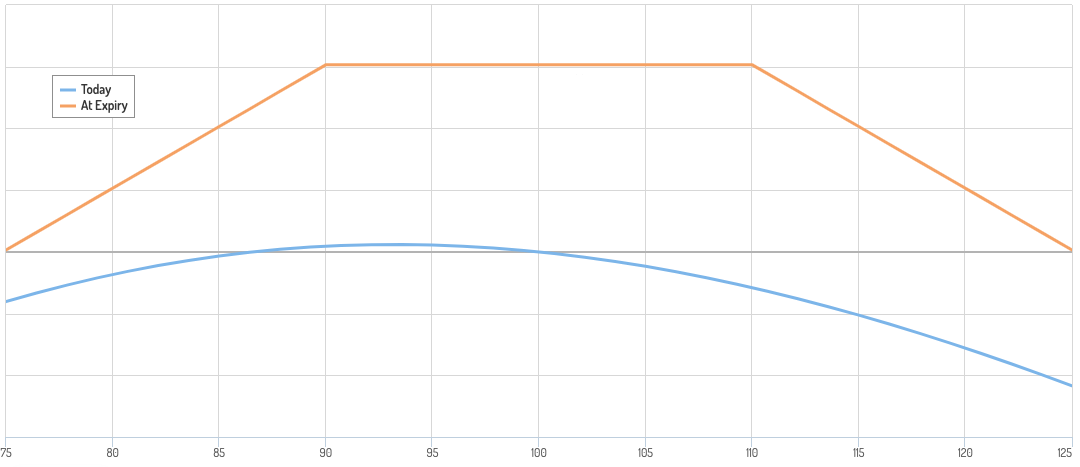
An example of a PnL curve in a Short Strangle position.
Brokerages know this. And as much as they like to couch things in terms that sound like they are protecting customers, in reality, they are covering their own asses by restricting your ability to sell naked short options in certain accounts (particularly cash and retirement accounts). Because they know if you can’t cover the losses on a naked short options position, the money comes out of their pocket. And, well, we know which pocket they value more.
So if we find ourselves in a situation where our trading account won’t allow us to sell naked short options, the margin for naked short options is too onerous, or if we just simply want to reduce the margin requirement for account management purposes, there is a simple, subtle little trick to gain the benefits of Naked Short Strangles.
Simply add some cheap, way out-the-money long calls and puts to our position. It’s quite possible we might find some options strikes we can purchase for 5 or 10 cents that will cut our margin requirement in half (or better). We can just treat those options as throwaway purchases, or consider them an extra commission on your trade. Whichever makes you feel better about it.
Then, we just manage the short options in the position of the Naked Strangle. Play defense or take profits the same as you would in a Naked Strangle.
Yes, these long call and long put hedges cost money and it adds up over time, but they allow us to get into trades and earn profits that we might not otherwise have been able to get into.
That’s a win.
Trade ’em Well,
Sean McLaughlin
Chief Options Strategist
All Star Charts, Technical Analysis Research
We had a resting GTC order filled at our profit target in the Paid-to-Play portfolio today: [Read more…]
The next new position in our Paid-to-Play portfolio is: [Read more…]
To access JC and Sean’s P2P options strategies, you must be a premium member of All Star Options P2P. Please login below.
Our Paid To Play options strategy has 3 core fundamental principles:
Together, these philosophies guide every single one of our trades. Because of that, we thought it’d be useful to explain the philosophy behind each principle. So we put together 3 short videos that do just that. Enjoy!
Why We Sell Volatility
Why We Trade Sector ETFs
How We Manage Risk
If you have any questions, please send them here.
You can view all trades and cash flow for this P2P account on our cash flow tracker found here.
We’ve adjusted a position in the Paid-to-Play portfolio today: [Read more…]