This is the video recording of the March 18th Town Hall Meeting w/ Willie Delwiche & JC Parets
03/18/21 2PM ET [Read more…]
Expert technical analysis of financial markets by JC Parets
This is the video recording of the March 18th Town Hall Meeting w/ Willie Delwiche & JC Parets
03/18/21 2PM ET [Read more…]
The latest All Star Charts Monthly Conference Call (subscriber link) is in the books and no doubt JC and the team had to chug a pot (or two) of coffee to get through that blizzard of charts.
Judging by the performance of the publicly traded Starbucks stock, our team are clearly not the only investors who rely on a caffeine boost to perform our best.
From the desk of Steve Strazza @Sstrazza and Ian Culley @Ianculley.
We recently held March’s Monthly Conference Call which our Premium Members can access and rewatch here.
In this post, we’ll provide a summary of the call by highlighting 5 of the most important charts/topics we covered along with commentary on each.
Let’s dive into it.
From the desk of Willie Delwiche.
Key takeaway: Investor optimism has been unwinding even as indexes have moved into record territory and breadth remains strong (NYSE new high list at its highest level since 2004). This week’s featured chart shows the spread between institutional and individual sentiment collapsing. This has tended to occur ahead of market strength, not weakness. While the risks from a strategic positioning perspective are undiminished (especially in the context of valuations and household equity exposure), the short-term and intermediate-term sentiment picture has improved in recent weeks as optimism has come off the boil. It looks to me like investor sentiment has moved off of the risk side of the scale and the weight of the evidence is turning more constructive not more cautious.
Sentiment Chart of the Week: Sentiment Spread, II less AAII
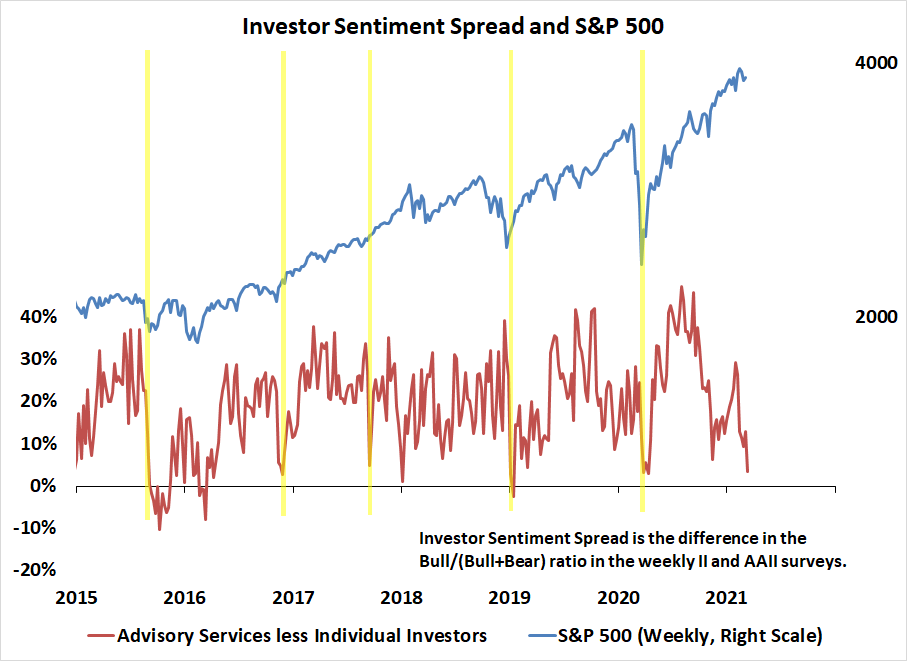
The current intensity of the advisory services move toward a cautious stance matched with a rise in individual investor optimism, implies a successful unwind of troublesome optimism that leads to better price action.
From the desk of Steve Strazza @sstrazza
At the beginning of each week, we publish performance tables for a variety of different asset classes and categories along with commentary on each.
Looking at the past helps put the future into context. In this post, we review the absolute and relative trends at play and preview some of the things we’re watching to profit in the weeks and months ahead.
The market continues to fire on all cylinders right now. Last week’s gains were nothing but a continuation of the same resiliency and momentum we’ve come to expect from risk assets over the last year.
As for what’s providing buying opportunities over the next few months and quarters, it is still strongly centered around cyclical areas pertaining to Energy, Financials, International Markets such as Canada, and Commodities, among many other areas we’ve been hitting on.
Last week’s price action continues to strengthen our view that we’ve reallocated into all the right areas. As such, our best course of action is to continue looking for the best risk vs reward opportunities in these leading groups.
This is the video recording of the March 2021 Conference Call.