This is the video recording of the June 30th Weekly Town Hall w/ Willie Delwiche.
06/30/22 2:00 PM ET [Read more…]
Expert technical analysis of financial markets by JC Parets
This is the video recording of the June 30th Weekly Town Hall w/ Willie Delwiche.
06/30/22 2:00 PM ET [Read more…]
For this week’s trade, we’re selling an $XLE August 65/85 Short Strangle for an approximately $2.75 credit. This means we’ll be naked short equal amounts of the 65 puts and 85 calls.
Get the full details, risk management procedures and targets for this trade here:
From the desk of Willie Delwiche.
Earlier this week, I laid out some similarities between now and 2008. From a price, liquidity, breadth and sentiment perspective, the echoes are there.
The comparisons keep popping up.
A couple of days ago, there was a chart showing that the ongoing decline in equity market value (relative to GDP) exceeds any other drawdown in the past 40 years with the exception of what was experienced during the Financial Crisis.
Today, it’s data from Gallup showing economic confidence is at levels only seen in 2008-2009.
I’m not saying that the market and the economy need to follow the course laid out in the wake of the Q4 2007 highs. But the more similarities we see, the more worthy it is of consideration. Put another way, until bulls provide proof that we are not following that path, it would be foolish (and perhaps expensive) to ignore it as a possibility. Don’t discount reality because it doesn’t fit with the narrative.
From the desk of Steve Strazza @Sstrazza
When investing in the stock market, we always want to approach it as a market of stocks.
Regardless of the environment, there are always stocks showing leadership and trending higher.
We may have to look harder to identify them depending on current market conditions… but there are always stocks that are going up.
The same can be said for weak stocks. Regardless of the environment, there are always stocks that are going down, too.
We already have multiple scans focusing on stocks making all-time highs, such as the Hall of Famers, the Minor Leaguers, and the 2 to 100 Club. We filter these universes for stocks that are exhibiting the best momentum and relative strength characteristics.
Clearly, we spend a lot of time identifying and writing about leading stocks every week, via multiple reports. Now, we’re also highlighting lagging stocks on a recurring basis.
From the desk of Willie Delwiche.
Key Takeaway: With pessimism at levels that elicit comparisons to the financial crisis, conditions are set for a meaningful bounce in equities. But at this point, the similarities appear closer to what prevailed in the first half of 2008 than what was seen as stocks moved toward their final lows in March 2009. With the NYSE and NASDAQ still seeing more new lows than new highs (31 weeks and counting) and breadth thrusts conspicuously absent, the backdrop offers little about which to get excited. Recent leaders are experiencing newfound weakness and new leaders are more defensive in nature. Investors have endured a succession of failed rallies in recent months, but that patience may wear thin. The burden of proof is on the bulls. Rally attempts that increase hope but offer little strength would fit the pattern seen during the financial crisis
Sentiment Report Chart of the Week: Mixed Messages From Bonds
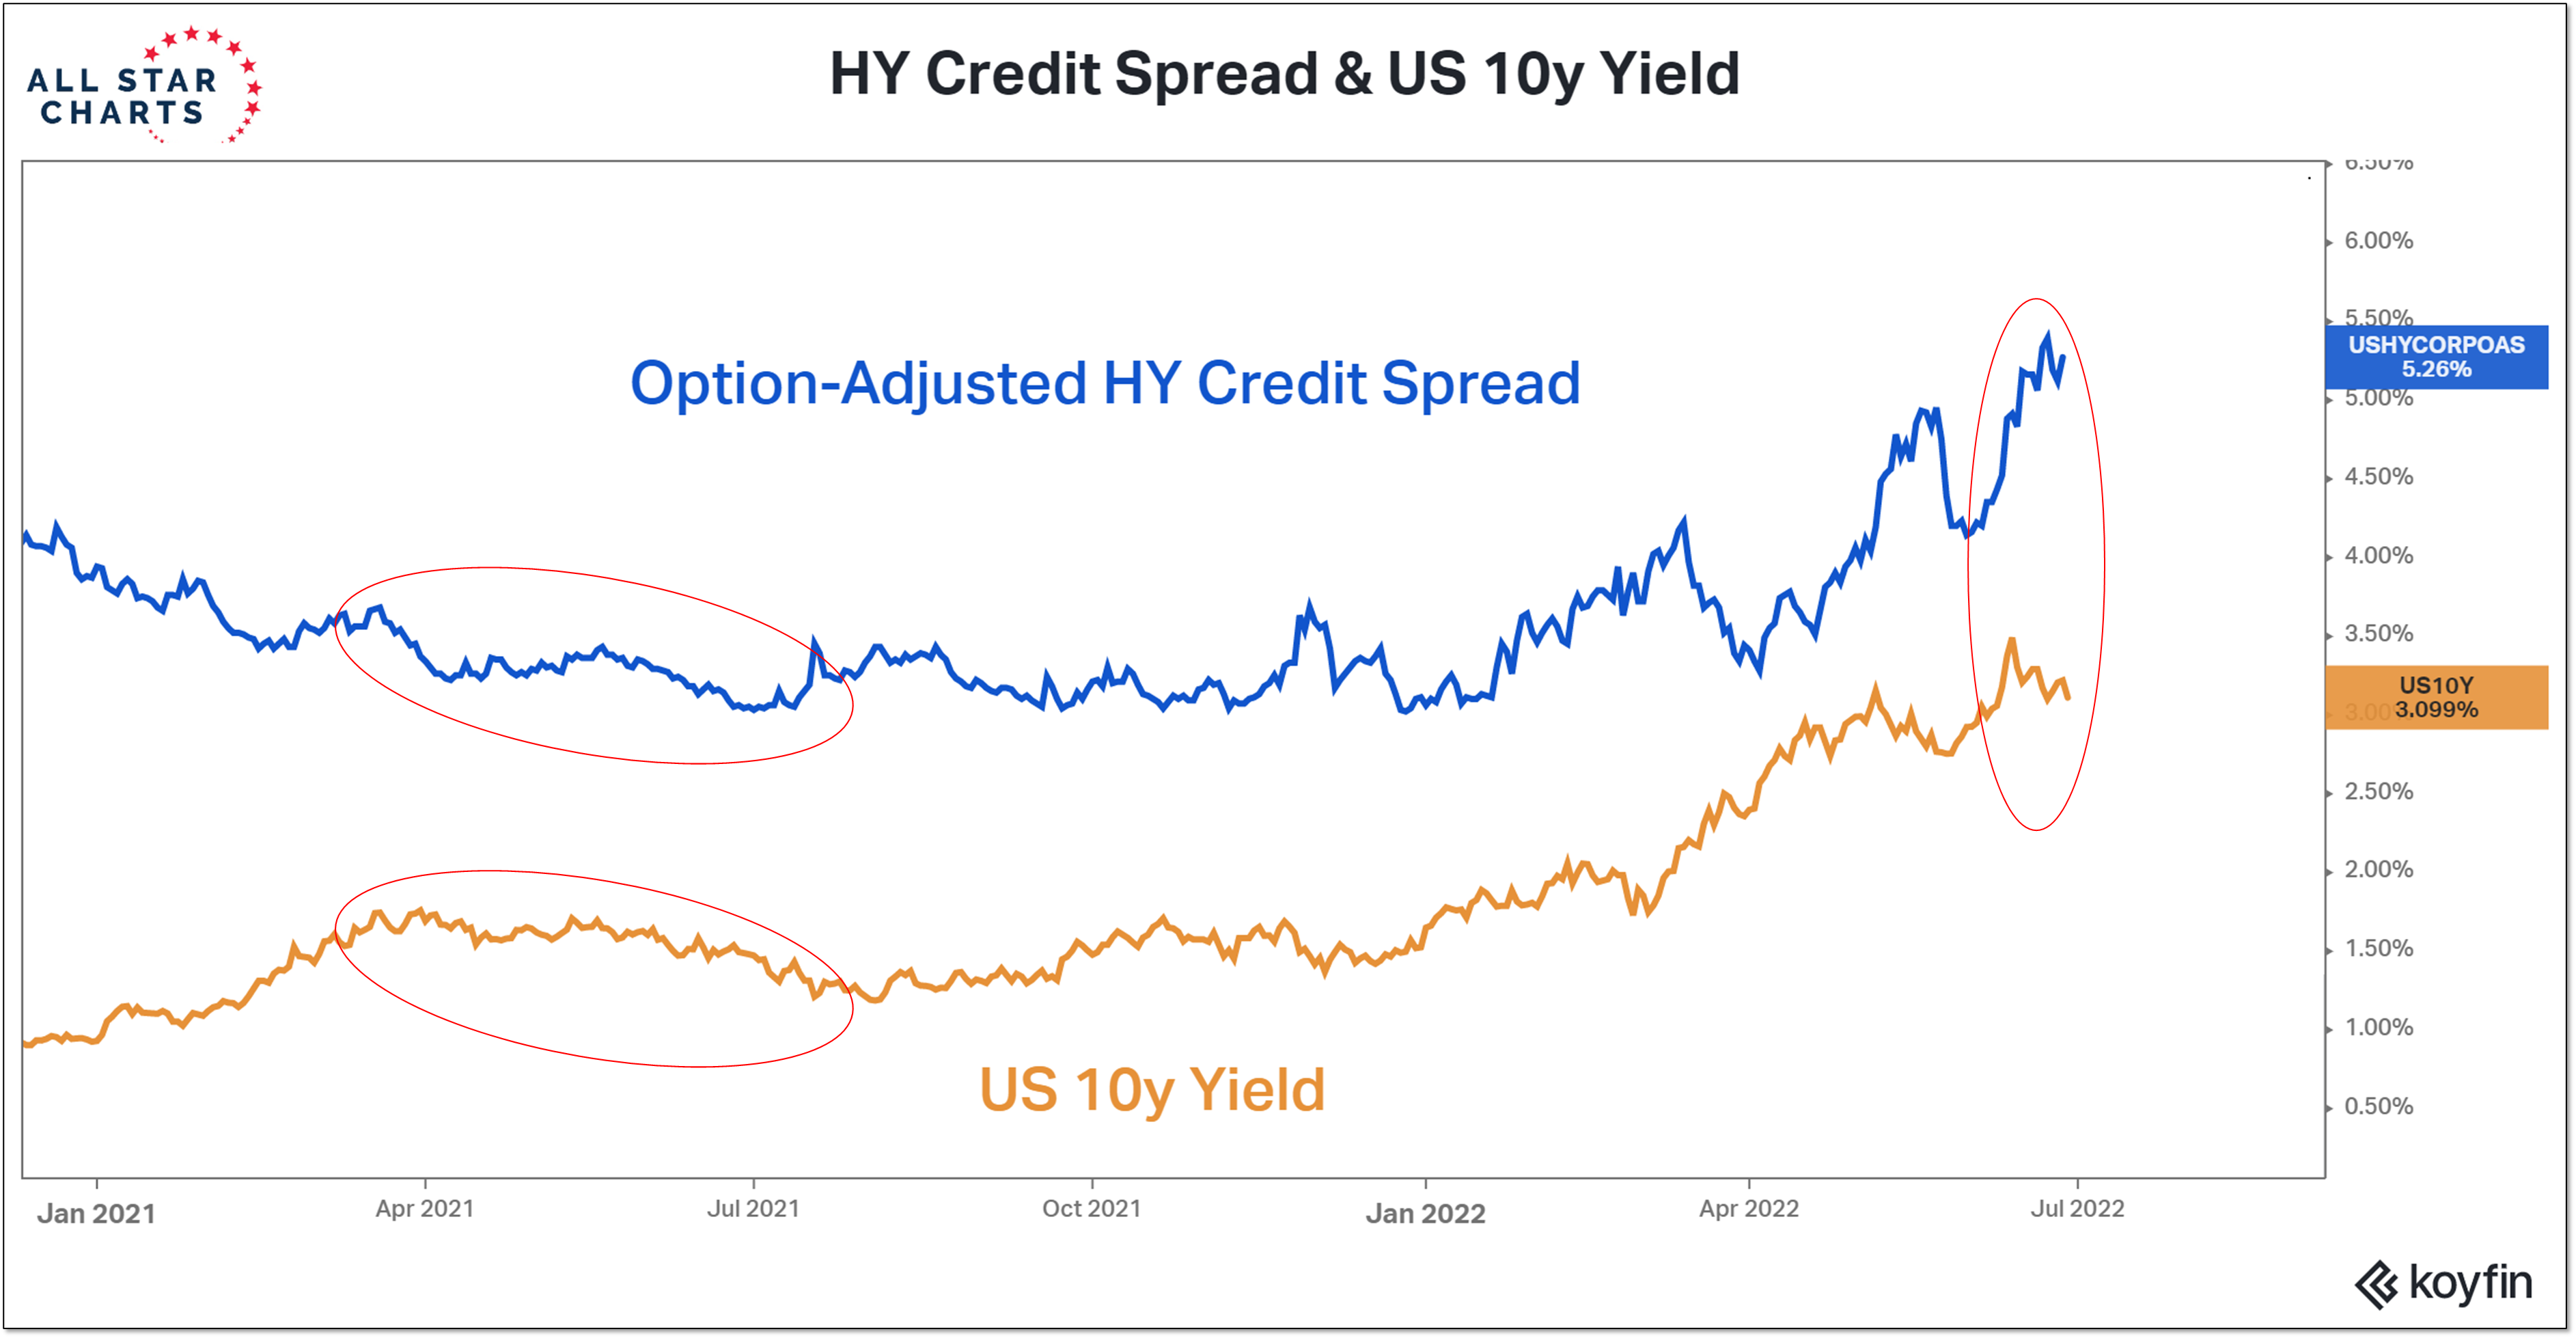
It’s been a rough first half for bonds. For now at least, Treasury yields have stopped crashing. When Treasury yields stopped rising and started to move lower in the first half of 2021, investor moods improved and risk appetites increased. Back then, however, lower Treasury yields were accompanied by narrowing credit spreads. Now, while Treasury yields have pulled back from their highest levels in over a decade, High Yield spreads are climbing to levels not seen since the COVID crisis. Junk bond ETF’s are trading at their lowest levels in more than two years. In this scenario, lower Treasury yields might not be a green light for growth areas of the market, but a move to safety that could include a re-evaluation of overall equity exposure (of which households have historically high levels) and/or an increased preference for defensive areas of the market.
Internally, we were talking yesterday about the energy space and the recent pullback in prices. While still the strongest sector in the market in 2022, this move off the highs has been notable.
Is the trend over? Or was that just the “hot money” taking profits?
I’m not sure we have a definitive answer to that question yet. It looks to me that the market is still sorting that out. And this condition of indecision, coupled with high implied volatility priced into options is combining into a nice opportunity to collect some options premium while energy figures itself out.
So we’re going to wade into the energy pool with a delta-neutral short-premium options trade.
[Read more…]
From the desk of Ian Culley @IanCulley
In almost every market environment, there are assets we want to buy and assets we want to sell. That holds even when we think the only option is to sell.
Recently, the strong buys have been in commodities and cyclical areas of the market, while bonds and the major stock indexes have sold off. That’s dramatically changed in recent weeks, though.
Now, all the major asset classes – bonds, stocks, and commodities – are under pressure, as bears come for the leadership groups. It seems nothing is immune to bearish price action these days.
Despite the broad selling pressure, there’s still an asset we want to buy: the US dollar. That’s right, the good old greenback! It’s one thing the bears can’t seem to crack.
If we think about it from an intermarket perspective, a defensive bid for dollars makes sense given the downside pressure on risk assets across the board. We don’t think it’s a coincidence.
Regardless, the USD is strong and shows no signs of changing anytime soon.
Last week, we outlined bases in the USD/NOK and the USD/SEK crosses. This week, we’ll highlight the Singapore dollar.


